The text below is an edited version of an Insight originally published on CRU online, dated 23 September 2026 by Alexander Chreky. For the full version, contact us or speak to a CRU expert about market intelligence and analysis relevant to your organisation.
The short answer: not in the near term, and not without higher costs. The US can diversify its potash supply over time, but it cannot quickly or cost-effectively replace Canadian material because Canada benefits from geographic proximity, established rail networks and extensive distribution infrastructure.
Renewed Canada–US trade tensions have brought US reliance on Canadian potash back into focus. Our analysis indicates that alternative sources can contribute to diversification, but they cannot readily match the availability, delivered economics or established route to market offered by Canadian producers. Canada is therefore likely to remain the US’s primary potash supplier over the medium term.
Why Does the US Rely on Canadian Potash?
The US relies on Canadian potash because the two markets are connected by a mature, deeply integrated supply chain. Canadian producers serve key agricultural regions through established rail corridors, terminals, storage networks and commercial relationships built over decades.
Most Canadian potash exports to the US originate from Saskatchewan, Canada’s principal producing region, and move efficiently towards Midwest fertilizer markets. This network is supported by distribution assets and established relationships with wholesalers, retailers and cooperatives.
Replacing Canadian supply is not simply a question of securing alternative tonnes. New suppliers would also need to replicate the infrastructure and commercial relationships required to deliver product reliably where and when US growers need it.
Can Seaborne Potash Imports Replace Canadian Supply?
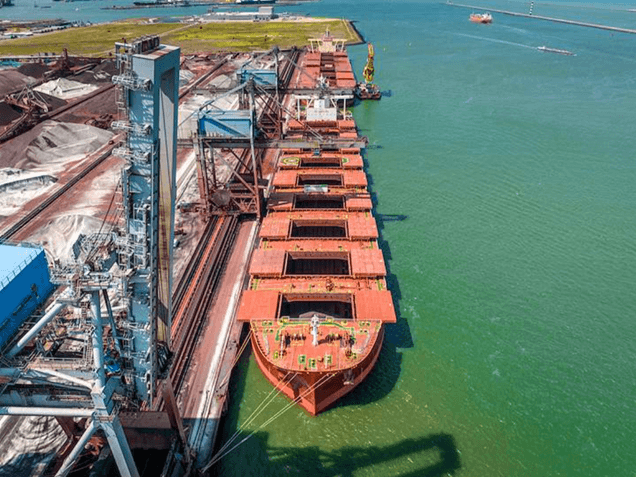
No. Seaborne imports can diversify US potash supply, but they cannot quickly replace Canadian volumes because inland logistics and established rail networks remain constrained. Russia, Belarus and other producers can ship potash to US ports, but moving material from coastal or river terminals to inland fertilizer markets is more difficult.
Port capacity can be expanded, but doing so requires planning, investment and time. The larger limitation is inland distribution. Barge capacity, railcars, loading facilities and storage infrastructure already serve other bulk commodities. Redirecting them towards potash would create pressure elsewhere in the supply chain.
Some coastal markets and areas along the lower Mississippi corridor could absorb additional imported material with limited disruption. Yet many fertilizer customers are primarily rail-served. Rebuilding established Canadian rail supply routes around imported cargoes would be costly, complex and slow.
Could Belarusian Potash Reduce US Reliance on Canada?
Only to a limited extent. Belarusian supply could broaden the US supplier base, but it is not a like-for-like replacement for Canadian potash. The removal of US sanctions on Belarusian potash may allow Belarusian tonnes to return to the market, but availability, logistics and long-term reliability remain uncertain.
Belarusian producers face longer and more expensive routes to the US than Canadian suppliers. The US Midwest is also a less attractive destination than several established overseas markets. Changes to European transit arrangements have added further logistical challenges.
Political risk matters too. US policy towards Belarusian supply has shifted over time, so buyers must weigh diversification benefits against the possibility of future disruption. Canadian supply, by contrast, is nearby, established and delivered through a dedicated cross-border network.
Can New US Potash Projects Replace Imports?
No, new domestic production could improve supply security but it cannot rapidly replace imported Canadian material. US domestic MOP production is limited, restricting how much potash can be supplied locally in the near term.
New projects require permitting, financing, construction and operational ramp-up before they can deliver meaningful volumes. Government support may improve their prospects, particularly where resources are well located relative to fertilizer demand, but it does not remove execution risk or shorten the path to production.
Domestic supply may become an important part of a longer-term diversification strategy. It is not a near-term solution to disruption in Canadian supply.
What Would Potash Tariffs Mean for US Farmers?
Potash tariffs or other restrictions would most likely raise costs and increase supply risk for US farmers. They would not resolve the infrastructure constraints limiting alternative supply before new routes and capacity are in place.
US growers benefit from access to a large, reliable and cost-competitive Canadian supply base. Diversification can improve resilience, but it requires sustained investment, policy continuity and coordination across ports, rail, storage and distribution.
For now, Canadian potash remains the most practical source of supply for the US. Attempts to replace it would take time and significant investment, while risking higher costs for farmers.
Want to discuss the implications for your business? Speak to an expert about the market intelligence and analysis relevant to your organisation.
© CRU. All rights reserved. This content may not be copied, reproduced, republished, distributed, or otherwise used, in whole or in part, without CRU’s prior written permission. Please refer to CRU's Terms and Conditions.